If mortgage rate headlines have made you put your Huntsville-area home search on hold, there's something important to know before you completely rule out buying:
The mortgage rate you see online isn't necessarily the rate you'd actually be offered.
National mortgage rates are useful for understanding what's happening in the broader market. But they can't tell you exactly what financing a home in Huntsville, Madison, or elsewhere in North Alabama would look like for you. Your credit, debt-to-income ratio, down payment, loan program, loan term, and other factors can all affect the rate you're offered. And right now, knowing those numbers could be especially useful for local buyers.
Huntsville-Area Buyers Have More Homes To Compare
While mortgage rates have been getting plenty of attention, something else has been happening here at home.
According to the Huntsville Area Association of Realtors, Madison County had 2,266 active single-family homes during the week ending September 19. That's 9.5% more inventory than the same time last year. Huntsville Area Association of Realtors
That doesn't mean every buyer should rush out and purchase a home. But it does mean that someone who stopped looking solely because of a national mortgage-rate headline could be overlooking homes that are currently available in their price range.
That's why your first question doesn't necessarily need to be: “What's the mortgage rate today?”
A better question may be: “What would buying a home actually look like for me?”
Once you know that, you can compare your financing options with the homes currently available in Huntsville, Madison, and the surrounding North Alabama market.
Your Actual Mortgage Rate Is Personal
Two buyers looking at the same Huntsville home won't necessarily receive identical mortgage offers. A lender looks at your individual financial situation when determining the financing available to you. Some of the factors that can matter include:
Your Credit Score
Your credit history can affect the rate and loan options available to you. Generally, stronger credit can help borrowers qualify for more favorable financing.
Your Debt-to-Income Ratio
Lenders also look at how much of your monthly income is already going toward debt. This is your debt-to-income ratio, or DTI. Your car payment, student loans, credit cards, and other monthly debts can all factor into that calculation.
Your Down Payment
How much you put down can affect your loan amount and financing options. And you don't necessarily need 20% down to buy a home. Different loan programs have different requirements.
Your Loan Program
Conventional, FHA, VA, USDA, and other loan programs don't all have the same requirements or pricing. For North Alabama buyers, it's worth asking a lender which programs you actually qualify for rather than assuming one type of mortgage is your only option.
Your Loan Term
The length of your mortgage can also affect your rate and monthly payment. That's why comparing loan options can be more useful than looking at one advertised number online.
Your Rate Isn't the Only Number That Matters
This is where the conversation becomes especially relevant when you're shopping locally. A mortgage rate doesn't exist by itself.
The price of the home, your down payment, loan program, taxes, homeowners insurance, and other costs all contribute to what owning that particular home may cost each month.
So instead of asking whether today's national rate is “good” or “bad,” it can be more useful to determine what monthly payment you're comfortable with and work backward from there.
That can help you establish a realistic price range before comparing homes across Huntsville, Madison, Owens Cross Roads, or Athens. or other parts of North Alabama.
New Construction Can Add Another Layer
Huntsville and Madison County buyers also have something else to consider: a significant new-construction market.
Some builders may offer financing incentives on select homes, including rate buydowns or closing-cost assistance. Those offers vary considerably by builder, community, home, lender, loan program, and timing, so they shouldn't be treated as a guaranteed benefit.
But they're another reason comparing the complete cost of buying a home can be more useful than comparing listing prices or national mortgage rates alone.
For example, Huntsville-area builders have recently advertised select-home financing promotions tied to specific loan programs and preferred lenders. Meritage Homes
A resale home and a new-construction home at similar prices could therefore have very different financing scenarios. That's something your lender and real estate agent can help you evaluate before you decide which option makes the most sense.
What About Seller Concessions?
Depending on the property and the terms of an offer, seller concessions may also be part of the conversation.
They can potentially help with eligible closing costs, which may change how much cash a buyer needs at closing. But concessions aren't automatic, and what is permitted depends partly on the loan program.
That's another reason it's useful to have your lender and real estate agent working together. One can help you understand the financing requirements while the other helps you evaluate what's realistic for a particular Huntsville-area property.
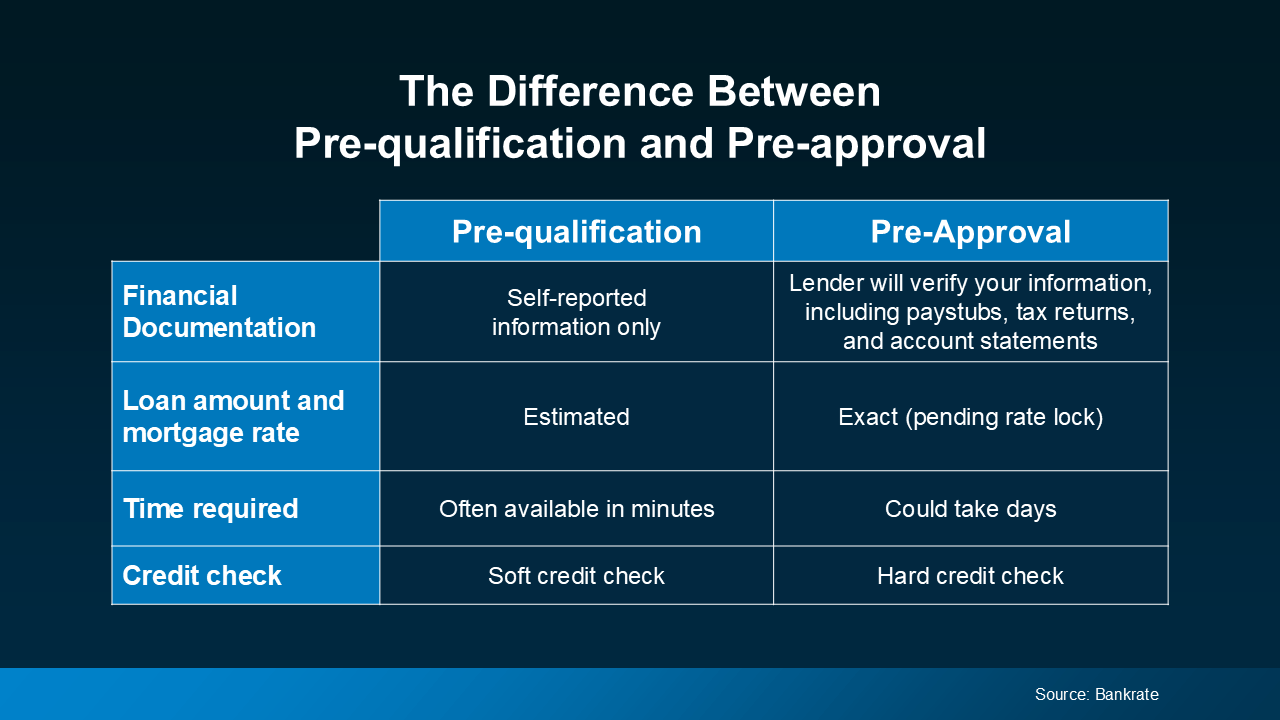
Should You Get Pre-Approved Before Looking at Homes?
If you're seriously considering buying, pre-approval can give you a much clearer picture than trying to estimate your buying power from rates you find online.
It can help you understand:
• What loan options may be available to you
• What rate you may actually qualify for
• Approximately how much you could finance
• What monthly payment range you're comfortable with
• How much cash you may need
• Which homes make sense to include in your search
Then, instead of scrolling through homes and wondering whether you can afford them, you can search with actual numbers in mind.
What Should Huntsville Buyers Ask Their Lender?
Don't feel like your only question has to be, “What's my rate?”
Try asking:
• Which loan programs should I compare based on my situation?
• How would changing my down payment affect my payment and rate?
• What price range keeps me within my preferred monthly payment?
• How would my payment change if rates moved up or down?
• Would paying down debt or improving my credit change my options?
• How should I evaluate a builder rate buydown or seller concession?
• What costs should I expect beyond principal and interest?
Those answers can give you a much more complete picture of what buying a home actually looks like.
Frequently Asked Questions
Is the mortgage rate I see online the rate I'll get in Huntsville?
Not necessarily. Online mortgage rates generally reflect broader market conditions. Your actual rate can depend on your credit, debt-to-income ratio, down payment, loan program, loan term, lender, and other details.
Are there more homes available to Huntsville-area buyers right now?
Madison County single-family inventory was up 9.5% year over year during the week ending September 19, 2026, according to the Huntsville Area Association of Realtors. More inventory can give buyers additional properties to compare, although availability varies by location and price range. Huntsville Area Association of Realtors
Do Huntsville homebuilders offer lower mortgage rates?
Sometimes. Builders may offer rate buydowns, closing-cost assistance, or other financing incentives on certain homes. Offers can have specific eligibility requirements and expiration dates, so buyers should compare the complete terms rather than assuming every new home includes an incentive. Meritage Homes
Should I wait for mortgage rates to come down before buying?
That depends on your individual situation. Your rate is only one part of your home-buying costs, and the homes, prices, incentives, and negotiating opportunities available today may also change while you wait. A lender can help you compare different financing scenarios before you make that decision.
Should I get pre-approved before touring homes in Huntsville or Madison?
If you're serious about buying, pre-approval can help you understand your financing options and establish a realistic price range. It can make it much easier to focus your Huntsville or Madison home search on properties that fit your budget.
Bottom Line
If a mortgage-rate headline is the only reason you've stopped looking for a home in Huntsville or Madison, don't let a national number make the entire decision for you.
Find out what your numbers actually look like first. You may decide that waiting still makes sense. Or you may discover that your financing options, combined with the homes currently available in Madison County, give you more choices than you thought. Either way, you'll be making that decision based on your budget and today's local market, not just a headline.
Dee Ellis | Rebecca Lowrey Group | RE/MAX Distinctive | Top 1% Nationally | 350+ Five-Star Reviews | Huntsville, Madison & North Alabama Real Estate Specialists.
Information is current as of October 2026 and is provided for general informational purposes. Mortgage rates, loan programs, qualification requirements, incentives, and financing terms vary. Speak with a qualified mortgage professional about your individual financial situation.